Vola: Cash Advance & Credit

Screenshots
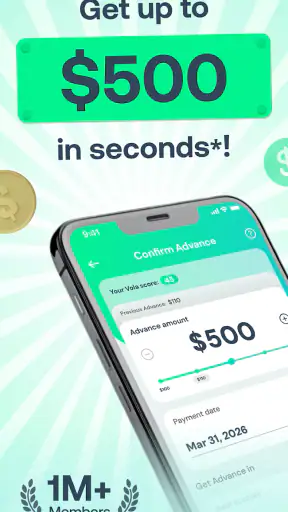
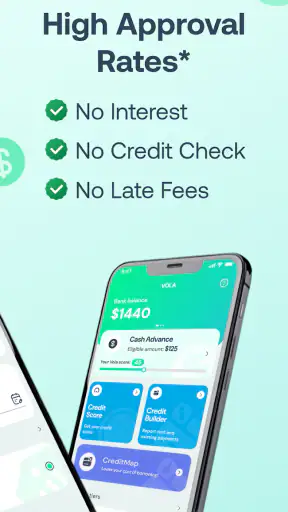
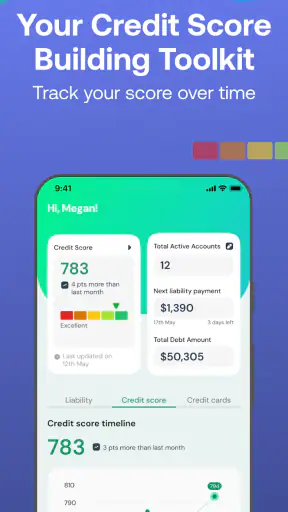
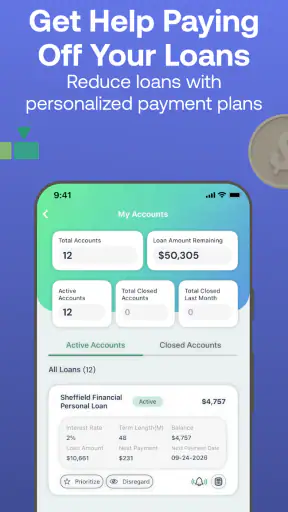
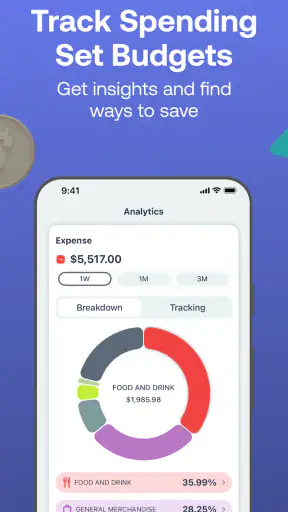
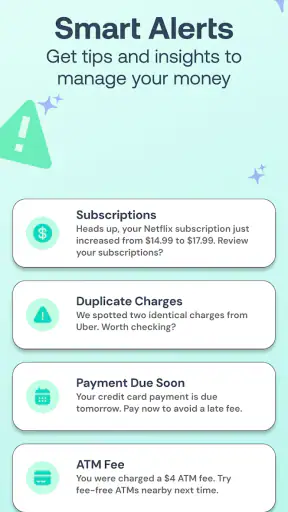
Details
- Rating
- 2.05K reviews
- Version
- 3.4.15
- Developer
- Vola inc.
Analysis by Norviv
If you are looking for a way to handle a short cash gap without opening a traditional credit application, Vola: Cash Advance & Credit is built around that exact situation. I approached it as a first-time user would: install the app, understand what it is asking for, connect the financial information it needs, and see whether the budgeting and cash-advance tools actually feel useful in everyday life. My overall impression is that it is more practical when treated as a financial planning companion than as emergency money that can be requested casually.
Vola is a free finance app from Vola inc. It is available for Everyone and has built a sizable audience, with over 500 thousand installs, a 4.7 average from around 11 thousand ratings, and roughly 2 thousand written reviews. Those figures suggest that the concept resonates with many people, but they should not be mistaken for a promise that every user will receive the same advance terms or experience the same approval result. The app’s value depends heavily on your personal financial situation and on how carefully you use its tracking tools.
What to expect before you request anything
The first thing I would clarify is what this app is and what it is not. It combines access to an instant cash advance with tools for building credit, setting a budget, and tracking spending. That makes it different from a simple banking app, where you mainly view balances and transactions, and different from a conventional loan application, which usually centers on a formal credit check and a longer repayment structure.
The promise of no credit check can sound straightforward, but it should not be read as “everyone receives money immediately.” Financial apps still need enough information to evaluate eligibility, understand account activity, and present the service responsibly. In practice, the important question is not only whether an advance is available, but also how it fits into the next few weeks of your income and expenses.
I found the strongest use case to be a predictable, temporary mismatch between payday and a necessary bill. Imagine your car needs a repair just before your next paycheck, while rent, groceries, and automatic payments are already accounted for. A cash advance may help bridge that narrow gap. It becomes a much weaker solution if you are using it repeatedly to cover a permanent shortfall, because the next repayment can simply create another gap.
The app’s finance category matters here. It is not entertainment software that you can explore without consequences. Every screen involving money deserves a slower read, especially when the app shows eligibility, repayment information, account connections, or credit-related options. I recommend opening it when you have enough time to review the details rather than setting it up while distracted or under immediate pressure.
Vola was released on January 23, 2019, and the current version is 3.4.15. It requires at least iOS or Android version 9, depending on your device platform. The age classification is Everyone, but that does not mean the product is suitable for every financial situation. A young or inexperienced user can still make an expensive mistake by treating a short-term advance as extra income instead of borrowed money that affects the next budget.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
The right mindset for a first-time user
I would begin with one simple rule: use the app to answer a specific question. For example, “Can I cover this necessary expense until my next income arrives without missing another payment?” That is a healthier starting point than opening it with no plan and taking the largest amount that appears available.
Before installing, have a rough picture of your upcoming obligations. You do not need a perfect spreadsheet, but you should know which bills are fixed, which expenses can move, and when your next dependable income is expected. This preparation makes the app’s budget and spending information much easier to interpret.
Another useful expectation is that the first session may feel more like verification and organization than instant relief. The app needs context to make its financial tools relevant. If you are uncomfortable connecting an account or reviewing transaction information, stop and read each screen carefully. A cash-advance service is not worth rushing through a decision you do not understand.
Setting up the app without losing control
After installation, I would treat setup as a financial check-in rather than a formality. Confirm that you are using the official app from Vola inc., review the account details you enter, and make sure the information reflects your current situation. Small errors in income or account information can make later budgeting less useful, even if the app itself is working correctly.
The most important setup decision is which financial account you use for the app’s tracking and eligibility process. Choose an account that gives a realistic view of your normal income and spending. A rarely used account can make your financial picture look incomplete, while an account shared with irregular transactions may make the results harder to understand. The best choice is usually the one that reflects the money you actually use for everyday obligations.
When reviewing permissions or account connections, I recommend asking what each connection helps you do. If it supports spending tracking, it should make your budget more informative. If it relates to advance eligibility, it may help the service assess whether the product fits your account activity. Either way, do not approve a screen automatically simply because you want to reach the next step.
Once the account is connected, give the transaction history a careful look. Categorization can be useful, but it is not a substitute for your own judgment. A recurring payment may be labeled in a way that seems reasonable to the software but misleading for your budget. A transfer between your own accounts can also look like income or spending if you do not interpret it correctly.
This is one of the less obvious strengths of using Vola thoughtfully: the setup process can expose financial habits that are easy to ignore in a normal bank balance view. A balance tells you what is available at one moment. A spending view can show that several small subscriptions, delivery orders, or convenience purchases are competing with a bill later in the month. That insight may be more valuable than the advance itself.
How I would build the first useful budget
Start with obligations that are difficult to change: housing, utilities, transportation, debt payments, and essential food. Then separate flexible spending from genuinely necessary spending. This distinction matters because a budget that treats every recent purchase as equally important will not help you decide what can be postponed when money is tight.
Look for timing, not only totals. Someone may have enough income for the month but still face a difficult week because several automatic payments arrive together. Tracking can help you notice that pattern. If the app shows spending by category but you ignore payment dates, you may still miss the practical problem the cash advance is meant to solve.
I also recommend leaving a small buffer in your own plan instead of budgeting every available dollar. An advance can cover one known expense, but it cannot protect you from every surprise. If taking the advance would leave your next income immediately committed to repayment and regular bills, the safer choice may be to reduce the expense, contact the biller, or wait until the payment is genuinely manageable.
Reaching the first meaningful success
For me, the first successful action is not simply receiving an advance. It is completing a clear, informed decision: either identifying a manageable short-term gap and using the app’s available option responsibly, or discovering through the budget that borrowing would make the following weeks worse. Both outcomes mean the app has done something useful.
If you are eligible for an advance, read the amount, timing, repayment details, and any applicable conditions before accepting. Do not rely on the word “instant” to mean that the money will solve every timing issue. Bank processing and your own payment schedule can still matter. Plan around the date you actually expect funds to be available, not the moment you tap a button.
Use the smallest amount that solves the specific problem. This is a practical difference between borrowing as a bridge and borrowing as a habit. If a smaller advance covers the repair, prescription, or essential purchase, taking more can create unnecessary pressure later. The app may make an amount easy to select, but your budget should decide what is sensible.
After accepting, immediately record the repayment in your personal plan. I would mark the expected withdrawal or repayment date alongside rent, utilities, and other fixed commitments. Then check what remains for groceries, transportation, and ordinary spending. This second look is important because the advance can feel like relief at first, while the repayment only becomes real when it competes with future expenses.
A useful workflow is to review the app once after the advance and again shortly before repayment. The first review confirms that the transaction appears as expected and that your budget reflects it. The second review gives you a chance to cut optional spending before the repayment arrives. This two-stage habit is more protective than checking the app only when you are already short of money.
Using the credit-building side carefully
The credit-building feature may appeal to users who are trying to establish or improve their financial profile, but I would not treat it as an instant repair button. Credit progress generally depends on consistent, responsible behavior and on understanding the product connected to that goal. Read the explanations inside the app and make sure you know what action is expected from you before assuming that simply installing or using Vola will change your credit position.
This is also where Vola differs from a standard budgeting app. A budgeting app may help you plan without involving borrowing, while Vola places cash access and credit-oriented tools in the same experience. That combination can be convenient, but it can also blur the line between improving financial habits and taking on another obligation. If your main goal is to control spending, you may be better served by using the tracking and budget functions while avoiding an advance unless the need is genuinely temporary.
For someone with no established credit history, the credit-related tools may be worth investigating. For someone already managing several credit products, adding another financial service may create more complexity than value. In that case, a direct conversation with a lender or a nonprofit financial counselor could be a better next step than adding another app to monitor.
Common points of confusion during everyday use
One likely confusion is the difference between eligibility and guaranteed access. Seeing an advance option does not mean you should assume the amount, timing, or availability will always remain the same. Financial circumstances change, account activity changes, and the app’s assessment may change with them. Treat any displayed option as something to review, not as a permanent part of your income.
Another confusion involves the spending tracker. A category total is useful only when it matches the way you make decisions. If a purchase is categorized incorrectly, adjust your interpretation before changing your budget. Otherwise, you might cut the wrong expense or believe you have more room in another category than you really do.
Transfers can also make a budget look healthier or worse than it is. Moving money between accounts is not new income, and paying a credit card is not necessarily new consumption at the moment it appears in your transaction list. When reviewing Vola, focus on the underlying purchase and the date your money leaves your overall finances, not only on the label attached to one transaction.
The phrase “no credit check” can cause another misunderstanding. It may make the service feel risk-free, but borrowing still has consequences. A cash advance can affect your available money later even if a traditional credit inquiry is not part of the process. I would judge the decision by affordability and repayment timing, not by the absence of a credit check alone.
Users may also wonder whether the app replaces a bank. In my view, it does not. Your bank remains the place where your money is held and where ordinary payments are managed. Vola is better understood as an additional layer for cash access, budgeting, spending awareness, and credit-related activity. Keeping that distinction clear helps prevent you from treating the app’s displayed balance or advance availability as your complete financial picture.
When a different option is safer
I would skip the advance if your income is uncertain, your next paycheck is already committed, or you are using advances to pay another advance. That pattern indicates a budget problem that short-term borrowing cannot solve. In those circumstances, negotiating a payment date, asking a service provider about a hardship arrangement, or seeking independent financial advice may be more appropriate.
A traditional bank or credit union may be a better choice when you need a larger amount, a longer repayment period, or a clearly documented installment structure. A regular budgeting tool may be better if your only goal is spending control and you do not want borrowing features in the same place. Vola’s convenience is most persuasive when the need is modest, short-lived, and easy to explain in your budget.
I would also avoid making a decision based only on the app’s rating. A 4.7 average and strong adoption are encouraging signs of a polished experience, but personal eligibility, repayment ability, and comfort with account sharing matter more than popularity. Finance apps can be well designed and still be unsuitable for a particular person at a particular moment.
The next step after your first session
Once setup is complete, give yourself one full spending cycle to learn from the app instead of immediately relying on its advance feature. Watch which categories grow faster than expected, note when automatic payments arrive, and compare what the tracker shows with your own bank records. This turns Vola from a one-time emergency tool into a way to make better decisions before a crisis appears.
A practical routine is to check upcoming obligations at the beginning of the week, review recent spending midway through the week, and reassess before any advance repayment date. The exact schedule is less important than consistency. Short reviews are easier to maintain than a large financial cleanup after you have already run out of room.
Before accepting any future advance, ask yourself three questions: What exact expense am I covering? What income will repay it? What essential bill could be affected if that income arrives late? If you cannot answer all three clearly, wait. The app can show you an option, but it cannot replace a realistic plan.
My final view is that Vola: Cash Advance & Credit is most useful for a first-time user who wants one place to examine spending, organize a budget, and consider a limited cash bridge without a traditional credit check. The free entry point and straightforward focus make it easy to try, while the combination of borrowing and credit tools means it deserves more care than an ordinary expense tracker. I would recommend it to someone facing a genuine, temporary timing problem and willing to monitor repayment closely.
I would not recommend treating it as a regular income supplement or installing it without a clear financial purpose. Used deliberately, Vola: Cash Advance & Credit can help turn a stressful money gap into a more organized decision. The most valuable result may be the moment you realize you do not need to borrow at all because the budget has shown you a safer way forward.
Frequently Asked Questions
01What is Vola: Cash Advance & Credit, and how does it work?
Vola is a financial app designed to help eligible users access cash advances and credit-building tools. After creating an account, you provide personal and financial information so the app can assess eligibility. If approved, available funds, repayment terms, fees, and delivery speed may vary. It is important to review the complete agreement before accepting any advance.
02Who can use Vola, and what information is required to apply?
Eligibility depends on factors such as your location, age, bank account, income, account history, and other criteria established by Vola or its financial partners. During registration, the app may request identity details, employment or income information, and permission to connect a qualifying bank account. Approval is not guaranteed, and requirements can change over time.
03How much does Vola cost, and are there any hidden fees?
The cost of using Vola depends on the specific product, membership option, advance amount, repayment method, and applicable partner terms. Some services may include subscription charges, optional expedited-transfer fees, or other costs. Before proceeding, carefully check the pricing screen, disclosures, and final repayment amount. Never assume that an advertised cash advance is completely free.
04When will I receive the money, and how is repayment handled?
Delivery time can depend on your bank, the transfer method selected, approval timing, weekends, and whether you choose a standard or expedited option. Repayment is generally connected to your linked bank account or another method shown in your agreement. Make sure sufficient funds are available on the scheduled date to avoid failed payments, additional charges, or possible account restrictions.
05Can Vola help build my credit, and is my information secure?
Vola may offer features intended to support credit-building, but results depend on the product you use, reporting practices, and your payment behavior. Credit improvement is not immediate or guaranteed. The app also handles sensitive financial and identity information, so review its privacy policy, permissions, security practices, and data-sharing disclosures before linking your bank account or submitting personal details.


